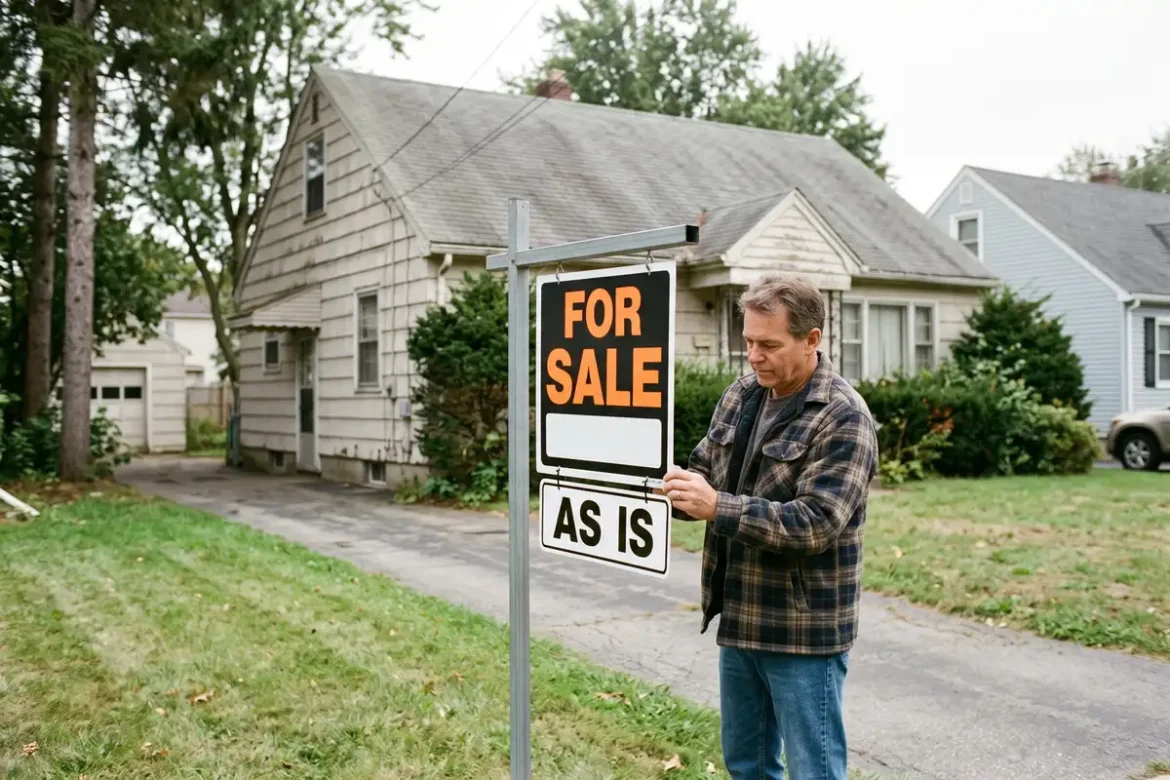
Owning a home can build wealth over time, but that value can shrink when bills and repairs pile up. If you need to sell quickly, fixing every problem before listing may not make sense. An as-is sale can sometimes help you keep more of what your home is worth.
The key is knowing your equity, comparing offers, and watching the calendar. A fast sale is not always the best deal, but waiting can also have a cost.
Continue reading to discover everything you need to know!
Know How Much Equity You Have
Equity is the difference between your home’s value and what you still owe on it. For example, if a home is worth more than its mortgage balance, the difference is your starting equity. Selling costs and other debts tied to the property can reduce what you take home.
Ask your lender for a current payoff amount. Then compare recent sales of similar homes to estimate a fair price. This gives you a clearer picture before you speak with buyers.
Remember that online estimates may miss damage or local market changes. A local agent can help you check the likely price range before making decisions.
Weigh Repairs Against Their Real Value
A fresh coat of paint may help a home look better, but major work can drain your savings. Roof damage, plumbing leaks, and old wiring often cost more than owners expect. Repairs may also delay your move.
Get estimates for the work that buyers are likely to notice. Compare those costs with the price you might gain after repairs. If the numbers do not work, selling as-is may be worth exploring.
Consider these costs before deciding:
- Contractor and material bills
- Extra mortgage payments
- Taxes and insurance costs
- Utilities during the wait
- Agent and closing fees
An as-is sale does not remove your duty to disclose known problems under applicable law. Buyers may still request inspections or negotiate the price.
Act Early When Foreclosure Is a Risk
Missing mortgage payments can put your home and equity at risk. In Texas, foreclosure can move quickly after required notices, so deadlines matter. Contact your lender as soon as you see trouble ahead.
If you want to skip the process of repairs, staging, and repeated showings, an as-is buyer may offer a simpler path. But a sale must close in time and provide enough funds to pay liens and required costs. It does not automatically pause or cancel foreclosure.
Ask your lender about repayment options or other ways to avoid losing the home. If a foreclosure sale is near, seek qualified legal or housing advice right away.
Compare Your Net Proceeds, Not Just Offers
A cash offer may come with fewer steps, but it may also be lower than a traditional offer. Request written terms and check fees, closing dates, and proof of funds.
Calculate what remains after paying your mortgage, liens, and selling costs. Compare that figure across options, including the cost of waiting. Do not sign under pressure.
Protect Your Next Move
Selling as-is can help protect equity when repair bills and delays would eat into your proceeds. It works best when you understand the numbers and have a realistic timeline. Take time to review your choices and seek help when deadlines are tight.
For more home-selling advice, explore our other blog posts.